National Energy Guarantee – A Cap And Trade Scheme

By Stacey Vacher, Edge Managing Director

The Energy Security Board (ESB) released a new version of the proposed National Energy Guarantee (NEG) following feedback from a variety of interested parties. The ‘Draft Detailed Design of the National Energy Gurantee: Consultation Paper’was released 15 June 2018. Also included was a paper by the Federal Government setting out the proposal for key areas of legislation which will be set at a Federal level. To support the papers a number of technical working papers were released to explore key aspects of the NEG.

The new version remains focused on reducing emissions in line with Australia’s commitment under the Paris Agreement and ensuring reliability. In addition to these key priorities, a third priority was to ensure that electricity remained affordable going into the future.

In regard to emissions, the largest change from the original version is a voluntary decoupling of the electricity contract written and the emissions levels. A retailer will still need to purchase contracts to keep emissions below a set threshold, however the emissions will no longer have to come from the same contracts that they have purchased electricity from. In theory, a retailer can purchase the output of a coal fired power station however not take on the emissions. That retailer would then be exposed to the emissions at the spot market which could be met through a separate contract with a renewable generator for only the emissions component.

In practical terms, the current proposed NEG is for all intents and purposes a cap-and-trade scheme. A retailer will be provided a cap on emissions. If they exceed that cap, they will have to purchase emissions credits from a low emitting source. If they are under the cap, they can sell their over commitment to other retailers. There will be the option to carry forward a limited amount of a previous compliance year’s over-achievement, for use in a later compliance year.

Reliability will come from AEMO’s forecast of supply adequacy. Each year, AEMO estimates supply adequacy for the following 10 years. If a material gap is identified, AEMO will notify liable entities (likely to be retailers and large users 5MW or greater) that there may be a reliability obligation. If the material gap is still present 1 year out, AEMO may start procuring demand response or additional generation. At this stage all liable entities must disclose their contract position to the AER. If a period with a projected reserve gap has demand above a one-in-two-year event, AER will monitor compliance against the reliability target. Each liable entity must demonstrate that they have procured sufficient qualifying contracts (such as fixed price contracts of a suitable nature, demand side management, or firm generation) to cover their position during peak demand.  It is proposed that a reliability gap will also trigger liquidity obligations for vertically integrated retailers to make financial contracts available to the market via the central exchange.  Furthermore, it is proposed that large users may transfer their reliability obligation to their retailer, but will have to ensure that their Electricity Sale Agreement addresses this. If a liable entity has insufficient qualifying contracts, penalties may apply. The level of penalties is undecided however a suggestion has been made to link to AEMO’s cost of procuring responses.

As with anything, the cost of both the emissions and the reliability components
of the NEG is likely to be passed on to consumers.

Modelling done to justify the introduction of the NEG assumes that the certainty brought by the NEG will reduce the risk premium of new power stations and cause more trading to occur. Both these factors would likely bring down energy prices (compared to business as usual). However, if the market does not see this as a much more stable investment environment, a reduction in wholesale prices is unlikely to materialise.

The NEG will expose consumers to both emissions and reliability costs. In terms of the emissions component, for most consumers this will be another pass-through cost added to their bills. Any trigger of a reliability gap could drive the cost of acquiring qualifying contracts (such as financial contracts) much higher in the relevant period. Whilst the liquidity obligation aims to counter this, we have concerns around how this will be enforced. It is critical to protecting against extortionate costs under this component. The current version of the NEG discusses a number of ways of addressing this and the ESB recommends creating a new repository for contracts as well as a market liquidity obligation. The repository would be able to report on all over-the-counter (non-exchange traded) products including volume and price. This may only be reported in aggregate for the market instead of identifying the parties to the deal. Very little detail is provided regarding the register.  The market liquidity obligation would require large vertically integrated retailers to make contracts available where there is a reliability gap. The retailers must offer to buy and sell contracts at a maximum spread so that prices can’t be set too high for buyers and too low for sellers. As with the repository there are few actual details on the liquidity obligation.

The emissions component has the potential to be highly variable from retailer to retailer. Each retailer will look at the generation they have produced and what emissions contracts they have purchased. If they haven’t purchased sufficient contracts for their entire load, they will assume to have procured the rest at spot. The spot emissions is calculated as the total emissions intensity of all generation less the generation volume already contracted in the emissions registry. A retailer or consumer is unlikely to know in advance how much will be forward sold and therefore the emissions costs can be highly uncertain. The retailer is likely to pass through this cost directly to the consumers, who ultimately wears the risk.

It is critical for all consumers who are agreeing electricity contracts with their retailers to understand how things such as the NEG are managed by their retailer and passed through. For the more sophisticated purchasers there is an opportunity to proactively manage some of this exposure themselves.

The Federal Government will continue to make laws regarding three key areas of the NEG. The key areas are:

  • Setting emissions targets
  • Treatment of emissions-intensive trade-exposed industries; and
  • The role of external offsets


There is a separate paper exploring these issues. The emissions targets are proposed to be expressed in tonnes of CO2-e/MWh. The target will be to meet a 26% reduction on 2005 levels by 2030. This is the target which was set at the Paris Agreement. There has been some criticism that if electricity only meets their proportion of the reduction, all industries will have to make the same reductions. The criticism is that it is much more economical to meet a greater share of the obligation from the electricity sector where alternatives to carbon emissions are cheaper than in other sectors.

The Federal Government is proposing to keep emissions-intensive trade-exposed industries exempt from the NEG obligations. This is to maintain international competitiveness.

This means that the rest of the electricity market will be required to purchase
additional volume to make up for the exemptions.

The paper also discusses the role of external offsets including the Australian Carbon Credit Units (ACCU) which are currently part of the Federal Government’s safeguard mechanism. They have also opened up to the possibility of allowing a limited number of overseas certificates be used for surrender.

There are still some large outstanding issues with both the ESB and the Federal Government’s papers. The ESB is pushing ahead to get a decision from the COAG Energy Council in August 2018. To facilitate this date, the turn-around time for comments are limited. The Federal Government is seeking comments by Friday 6 July 2018 and the ESB wants their comments by 13 July 2018. The commencement date of the NEG is due to be 1 July 2020.

If you would like to understand more about the NEG and the potential impact it may have on your energy portfolio moving forward, please visit edge2020.com.au or alternatively you can call one of our team directly on 07 3905 9220 or on 1800 EDGE ENERGY.

STAFF PROFILE – Melitta Springer

Melitta has spent over a decade working in the energy sector in roles including Retail Pricing Analyst, Account Manager and Customer Relationship Manager. As Portfolio Manager at Edge, she focuses on building and maintaining strong relationships with clients and key stakeholders. She’s unwavering in her commitment to using the Edge’s efficiencies and insights to deliver solutions that save clients time and money.

What is the best piece of advice you have ever received?

It’s not necessarily advice, but a quote from Winston Churchill has stuck with me over the years.  “Continuous effort – not strength or intelligence – is the key to unlocking our potential”.

It is the little things that we do each day that add up to big changes.

Name a place you have never been to and would like to visit. Why?

I would really love to travel through South America.  The culture, the food and the history all entice me to travel there.  Highlights would certainly be trekking through the Amazon and seeing Machu Picchu.

Who or What inspires you?

Communities and social enterprises that are working for the improvement of the environment and society inspire me.   I have made many changes in my life that impact both myself and my daughter and I hope to encourage others to make changes by having conversations and sharing my personal experiences.  If we all could make one positive change towards the environment every day, imagine the global impact.   The actions of individuals can have far-reaching effects.

What is one of the biggest challenges facing energy customers today?

In such a volatile energy market, reducing energy costs is a serious challenge for businesses.  With pricing in both the gas and electricity markets doubling in recent years, costs that would have generally been low percentage OPEX are now being highlighted by management as critical areas to review.

Energy efficiencies, renewables, Power Purchase Agreements and on-site generation (including solar PV and battery storage) all tend to be at the forefront of conversations with clients and prospective clients as they try to navigate the best path forward for reducing energy costs for their businesses.

What does a typical day look like for you at Edge?

On any given day I will have a number of scheduled client deliverables which could include weekly and monthly market reporting, site specific accruals and reconciliation reporting.  Beyond this, I work through queries from my clients that may include contract reviews, data analysis or third-party communication with Network Providers and Retailers.

RSPCA ADOPT A PET!

Roger, RSPCA Adoption Cat

For the 50,342 animals that arrived at the RSPCA Queensland centre over the past year, it was a second chance at life.  One of those lives belonged to 3 year old ‘Roger’, a domestic short hair ginger tabby cat.  Roger had been surrendered by a family that no longer wanted him and after spending 4 months in the Wacol RSPCA shelter, was re homed.  Roger was given another chance of life after being adopted by Kristy McGrath, our Head of Operations & Client Delivery, at the recent RSPCA Pop Up Adoption Day in South Brisbane.  Already having two dogs and two horses, adopting Roger from the RSPCA was an easy decision when it came to adding to her animal family.

Edge has always been a big supporter of the animal community and charity foundations.  And whilst choosing the right pet is fun and exciting, it takes time, planning and lots of research. To make the process easier, the RSPCA has introduced Adopt a Pet, a national website that lets you view some of the animals waiting to be adopted at RSPCA locations across Australia.

Join Edge in giving these animals another chance of life.  Visit their website, and give a dog, puppy, cat or kitten a second chance to find their loving home!

STATE OF THE ELECTRICITY MARKET – Q118 MARKET OVERVIEW

By Thomas Dargue, Edge Manager of Markets & Advisory

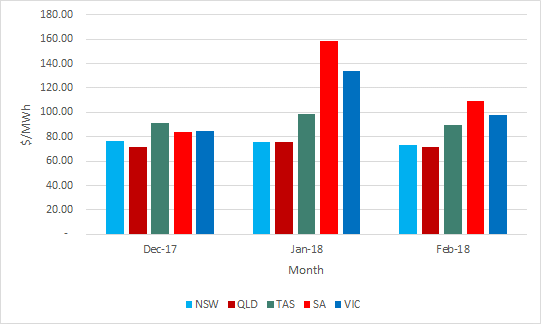
In this summer edition of the market update we look at some of the issues which is causing price differences in wholesale prices across the east coast of Australia. Since the start of summer, the divide has mainly been across the Murray river with QLD and NSW to the north and VIC, SA and TAS sitting to the South.

The summer started in December with modest spot prices across all the regions. The region with the highest price was TAS at $90.96/MWh with the lowest price being QLD at $76.56/MWh. The interconnectedness of the market means that prices in NSW was similar to QLD while SA and VIC were closer to TAS. The prices in NSW started deviating from the southern market as the interconnector with VIC became increasingly constrained. Throughout January there were large price spikes in SA and VIC increasing the average price south of the Murray. The constrained interconnector meant that the prices never travel north and both QLD and NSW had modest prices.

Figure 1 Average NEM spot prices.

Tasmania had similar prices throughout the three months however these seem to be too high for the State Liberal Government. There is an election in Tasmania 3 March 2018 and one of the policies put forward by the State Liberal Government would be a split from the NEM. TAS would still be physically connected through Basslink however would not be subject to the price setting mechanism set out for the NEM. The State Liberal Party is expecting this to result in lower wholesale prices for TAS.

Prices for summer to date has been higher in SA than any other state however there haven’t been any black outs. This is in part due to the operation of a new 100 MW battery installed by Tesla which provides energy during peak times as well as support for frequency. With an election in SA 17 March 2018 the incumbent State Labor party made its own electricity policy announcement. It would seek to further partner with Tesla to install 50,000 rooftop solar panels and batteries. When combined this would create a virtual 250 MW power station.

The Energy Security Board (ESB) realised its Draft Design Consultation Paper on the National Energy Guarantee (NEG). The NEG seek to find a balance between affordability, reliability and carbon reduction which could be politically acceptable. With the number of schemes already rejected by the Federal Government, the ESB has managed to come up with a scheme which could get bi-partisan support. At this stage there is quiet optimism however there are large concerns over the effect on contracting going forward. The ESB is looking for written submissions by 8 March 2018 and have the final design by the second half of 2018.

The forward prices generally reduced for 2019 as spot prices were less volatile than seen in previous years over summer. The exception was SA where there is still uncertainty around security of supply.

Table 1: ASX prices for Calendar Year 2019

NSW QLD SA VIC
1 DEC 2017 80.75 68.11 92.94 86.55
28 FEB 2018 76.38 64.03 94.36 82.90


The forward prices were lowest in QLD where we expect a large amount of new renewable generation to be built. Concerns over sufficient supply in other regions kept prices higher.

Despite higher forward prices and the highest average spot prices in the NEM, a hydrogen electrolyser will be built in Port Lincoln, South Australia. This will produce hydrogen using excess wind and solar (i.e. when prices are low) to produce hydrogen both to power a 10 MW gas turbine but also for export purposes. By using power intermittently, it is able to ramp up during low prices and not run during high spot prices which will also stabilise the grid and allow more wind generation to be dispatched in the region (wind in SA is currently being curtailed by AEMO to avoid frequency issues). It seems counterintuitive to put an energy intensive industry in SA however for very flexible consumption of electricity who are able to take advantage of low, or even negative, spot prices there is opportunity in the state.

If you would like to discuss the electricity market outlook and potential impact to your electricity portfolio, please contact Thomas on 07 3905 9226 or on 1800 EDGE ENERGY.


Gas Market Update

By Nick Clark, Energy Analyst

ACCC GAS INQUIRY – INTERIM REPORT

The ACCC released the second interim report into gas supply arrangements in December 2017. In the initial report (released September 2017) it was reported that there would be shortages in gas supply available to east coast consumers in 2018. The report found that buyers of gas were receiving offers from a reduced number of suppliers and that prices offered were above the ACCC’s benchmark prices. It was also noted in the report the lack of participation from the QLD LNG producers in the domestic market. This reported lack of participation from the LNG producers prompted the Federal Government to act. The result was the creation of a Heads of Agreement with the LNG producers which would see additional gas allocated to the domestic market.  According to the second Interim Report (released in December 2017), since September 2017 the QLD LNG producers contracted 42 PJ’s of gas under long-term supply agreements to domestic buyers for supply in 2018. The majority of this gas was sold to aggregators and retailers. The ACCC’s forecast for the balance of gas was also updated in the second interim Report and resulted in an improved balance of 75 PJ’s. The change in balance has been driven by a 12 PJ increase in supply and the lower demand from the LNG producers (63 PJ). Whilst on face value the market has gone from deficit to surplus, the balance remains tight and subject to gas producers meeting forecasts.

Table 1. Gas Balance

September Expected Domestic Demand Scenario (PJ) December Expected Domestic Demand Scenario (PJ)
Supply 1,901 1,913
Domestic demand 642 642
LNG demand 1,314 1,251
Projected Balance -55 20

Source: ACC Gas Inquiry Report – Second Interim

According to the report, there continues to be a shortage of production in the southern states to meet demand (SA, NSW, ACT, VIC and TAS).  As a result, these states will continue to rely on gas transported from QLD.  Additional costs to transport gas from QLD to VIC and SA are currently between $2/GJ and $4/GJ. Transporting gas south from QLD is not only expensive but due to limited firm capacity in key pipelines is not always feasible. Firm capacity in these key pipelines is predominately booked by the major retailers. It was examined by the ACCC if the major retailers were making spare capacity available to other users on major pipelines through secondary trading. It was found that on the major pipelines this was not the case however, there was some evidence to suggest this may have been occurring on the less critical pipelines. Since the ACCC investigation it has been observed that the retailers have increased the availability of spare capacity to other pipelines participants improving competition.

FIRM CAPACITY – The amount of transmission guaranteed to be available to the shipper – up to MDQ & MHQ every day

AS AVAILABLE CAPACITY – This capacity is typically spare contracted capacity that is offered on the secondary market. As can be disrupted or delayed, it is not necessarily guaranteed.

The ACCC expects that transportation costs will start to come down as regulatory reforms begin to take effect.

Domestic prices to large C&I customers were around $16/GJ in early 2017 and even higher for smaller business customers. Since July 2017, it was reported that prices between $8/GJ and $12/GJ were achieved by large C&I customers.


GAS PRICES

Across each of the east coast trading hubs January average prices were higher than the Q417 average.

Table 2. Hub Prices

Adelaide price ($/GJ) Brisbane price ($/GJ) Sydney price ($/GJ) Melbourne price ($/GJ)
Q417  $7.14  $7.68  $7.12  $6.20
JAN18  $ 8.10  $8.16  $9.71  $8.64
FEB18 $9.29 $7.33 $9.71 $8.67

Source: AEMO

Recent news

Four projects have received funding from the South Australian Plan for Accelerating Exploration (PACE) gas program’s second round. The program was designed as part of a suite of measures to increase investment in local gas production and to ease price pressure in South Australia. The four projects to receive funding were:

  • $6.89 million for the Santos-Beach Cooper Basin project to deploy a heat-energy recovery system to offset natural gas used to run the Moomba petroleum processing plant
  • $5.26 million for the Senex Cooper Basin Gemba exploration/appraisal project
  • $6.89 million for Beach /Cooper Energy’s Dombey project in the Otway Basin
  • $4.95 million to the Rawson/Vintage Nangwarry project in the Otway Basin

Under the program, gas extracted through the PACE program must first be offered to local electricity generators, enhancing the affordability of supply. Whether the cheaper gas is passed onto end customers by the gas generators is more difficult to say.

Moving north to QLD, Senex’s 100% owned Western Surat Gas Project recently recorded a significant milestone, which was an all-in well cost of $1.2 million. The strong results have promoted Senex’s reputation in the market and has encouraged Project Atlas, which is another Surat Basin project expected to bring first gas in 2019, to be sold to the domestic market.

On 12 December Independent Scientific Inquiry into Hydraulic of Onshore Unconventional Reservoirs in the Northern Territory releases its draft final report. The overall conclusion of the report was:

“The overall conclusion of the Report is that risk is inherent in all development and that an onshore shale gas industry is no exception. However, if the recommendations made in this draft Report are adopted and implemented in full, those risks may be mitigated or reduced – and in many cases eliminated altogether – to acceptable levels having regard to the totality of the evidence.”

Since the release of the draft final report the panel has engaged with the Northern Territory community, Government, Industry, environmental groups, and other relevant stakeholders about the content of the report. This is the last opportunity for the Territorians to express their views on the inquiry.

The final round of regional consultations concluded mid-February and the final day for submissions due to the panel is 25 February 2018. At this stage the panel has committed to providing the Final Report to the government in March 2018.


If you would like to know more about what is happening in the gas market and how your business may be affected, please call Edge on 07 3905 9220 or contact your Edge Portfolio Manager.

Renewable Generation Off-Takers On The Rise

By Stacey Vacher, Edge Managing Director

We are seeing a significant increase in large users exploring renewable generation off-take opportunities. This includes behind the meter build-own-operate or power purchase agreements (PPAs), and offsite commercial arrangements otherwise referred to as corporate PPAs, synthetic PPAs, or simply contracts for difference (CFDs). The reasons are mixed. Some are looking to meet future corporate emissions targets.  Others are aiming to achieve lower energy costs. Some are looking to further diversify procurement strategies. All are fearful of missing out on the next big opportunity.

Edge are actively involved in taking large electricity users through the process of assessing, and where feasible, entering into arrangements with renewable generation. We provide a range of services covering everything from practical energy market expertise and advice through to strategy development and implementation and even transaction support. This is particularly helpful where the renewable generation forms part of a new or existing electricity sales agreement as negotiating terms can otherwise be difficult. Large mining, transport, agricultural and manufacturing clients are amongst those leading the way. Elsewhere in the market, we have all seen the announcements from users such as Sunmetals, Telstra, Onesteel, Sunshine Coast Council, Universities and smaller aggregated buying groups (to name a few).  The list is growing rapidly.

Looking beyond the consulting jargon, the diverging spectrum of price forecasting curves, and the race for the next Renew Economy or AFR headline, are these deals really the right thing for your business? Absolutely, they can be. But they may also not be. It is critical that you understand the current electricity market including renewable generation, and the potential financial benefits and costs these opportunities can bring to your business.  Edge can work with you to identify and understand these critical components to ensure you take the right direction when considering renewable generation in your portfolio. It is important to consider how adding renewable generation will affect your current position including your electricity contract.

You’re shown the aggregate market price of electricity and LGCs today and a comparable renewable generation blended off-take price.  Depending on the region and generation project, you’re looking at $130 to $150/MWh on the market against $60 to $70/MWh for renewable generation. The savings appear staggering. But some things may be too good to be true and the devil certainly is in the detail.

Term

These opportunities are long term propositions, typically seven to twelve years though can be as long as twenty years or as short as three years. A lot can happen in this time and only one thing is for certain, things will change.  Supply and demand profiles will change. Project and market pricing will change.  Governments and their priorities and policies will change.  Depending on your corporation’s view on being quarantined (for better or worse) from these changes, you may lean towards all longer term, a blend of longer and shorter term, or no longer term contracting.

Project Risk

Renewable project developers are everywhere. Long haul business class cabins are filled with them. Virtual office spaces have never had it so good.  But not all have the experience in developing projects in Australia, therefore lacking experience with NEM based network service providers (NSPs), Australian government and council bodies, EPC contractors, and the like. Go to any NSP public forum and you’ll see first-hand the challenges that face NSPs around renewable project connections. Be it sheer volumes of enquiries, network or timing constraints, project risk is rife. An off-take start date can quite literally make the difference between a business case supporting the opportunity or not.  Partnering with a credible counterparty and / or managing project risk is critical.

Price Forecasting

The harsh reality is, we spent 2017 being privy to too much price forecasting that existed simply to suit the narrative. You can make generation opportunity in or out of the money with a suitable forecast curve.   Price forecasting plays a significant role in assessing the optimal renewable generation project and the potential value and risk that sits within in it.  Projecting future spot prices is a quantitative minefield. There are a few well known modelling tools utilised by equally well-known consultants to generate spot price forecasts in the NEM.  Edge also generates in house spot price forecasting. Whomever you utilise to produce future price curves, challenge the inputs and demand shape on the outputs. With significant volumes of renewable generation set to enter the NEM and aging fossil fuel plant preparing to exit, we are moving into a new dynamic in the NEM.  The characteristics of the supply curve are changing considerably. As storage technology advances, the behaviour of intermittent generation too will advance.  As users are forced to explore demand side management (DSM) opportunities, the demand profile will also change.  Five-minute trading intervals will change supply and demand behaviour. To adequately assess any renewable generation or off-take opportunity it’s about the expected spot outcome and the sensitivity around this result, measured in each trading interval. Having a high and low case based around randomly selected forced outages doesn’t even begin to address the uncertainty in the electricity market. Even if a project is priced firm to a flat mega-watt (MW) profile, understanding the potential impact to the shape the merits of the firm pricing against other procurement strategies.

Regulatory Risk

Either we are getting older and more in tune with the volatile nature of politics, or politics has taken regulatory racket ball to the whole next level. Investment in new generation in the NEM has previously stalled due to policy uncertainty.  The more recent run of high electricity prices is testament to this. Just when the market does what markets are supposed to do and responds to price drivers with new entrants and technological advancements, our policy makers inject more uncertainty in the form of a National Energy Guarantee (NEG). The end game of the NEG is noble. To promote that we meet our international emissions commitments, whilst ensuring our electricity is reliable, secure, and of course affordable.  Achieving this whilst not forcing any politician to back down from previously stated principals. The practical application of the proposed design however is a very long way from readiness, and in its current form is alarmingly at risk of causing segregation and market power that can only result in higher energy prices.  Meanwhile the Government has cast a dark cloud over the application of the Renewable Energy Act, and specifically the ability for renewable energy projects to receive certificates if they are commissioned after the target date of 2020.  It’s a risk that not even all the developers are aware of.  As an off-taker you must make it your priority to be across it and manage it.

Shape Risk and Firming

Renewable generation is intermittent.  The question remains; what happens when the sun isn’t shining, or the wind isn’t blowing?  Storage solutions are on the rise, but the dispatch limitations and costs still make it very challenging to get the business case across the line.  Clients who are looking to integrate renewable generation in their portfolio must be aware of the risks associated with shape risk.  This includes managing their shape with the overall shape of their hedge portfolio (tenure, type, etc.) and spot risk.  How can one best introduce intermittent generation (or intermittent offtake) into a portfolio, and what is the most efficient and effective means to manage this risk.  Firming products are one of the most sought-after products in the NEM today. Physical solutions have their role in mitigating some shape risk and include DSM, onsite generation, and storage solutions. Financial solutions also stand to play a significant role, including both traditional electricity derivatives and weather derivatives.  Securing firming products is undeniably challenging.  Hydro and gas generators have five-minute settlement to consider.  Furthermore, gas generators need to clear long-term fuel supply hurdles.  Coal generators may not be so eager to firm a product that will ultimately stand as the perfect competitor to their own offtake. Edge work closely with clients to understand shape risk and firming solutions.  We actively engage with the wholesale market to seek and deliver solutions that work best for each individual client.

Settlement

Settlement of third party PPAs need not be complicated.  In fact, it need not be independent of your electricity invoices.  Edge has negotiated PPAs that settle directly between the project and off-taker. We have also negotiated settlement services with retailers to ensure consumers benefit from longer term renewable generation whilst still only receiving monthly invoices form their retailers.  Understanding the cash flow implications and adequately addressing credit counterparty risk is all critical but certainly manageable.

Accounting

There are accounting implications as to how these arrangements are structured.  Whilst we are across these due to our involvement in large offtake deals, we are not an accounting firm.  We would strongly recommend that any consumer exploring these opportunities ensures their accounting advisors are across implications such as implied lease agreements, impacts to the balance sheet, and / or derivative accounting.

Whatever stage your organisation is at in considering Renewable Energy as a part of your electricity portfolio, Edge can help. If you would like to learn more about Edge, please visit edge2020.com.au or alternatively you can call one of our team directly on 07 3905 9220 or on 1800 EDGE ENERGY.

EDGE LIVE now displays invoice reconciliation & accruals outcomes

James Webster, Edge Software Development Manager

In addition to Snapshot functionality which provides you with information relating to your current and forecast spend and consumption, you can now access your Invoice Reconciliation and Accrual outcomes instantly within Edge Live.

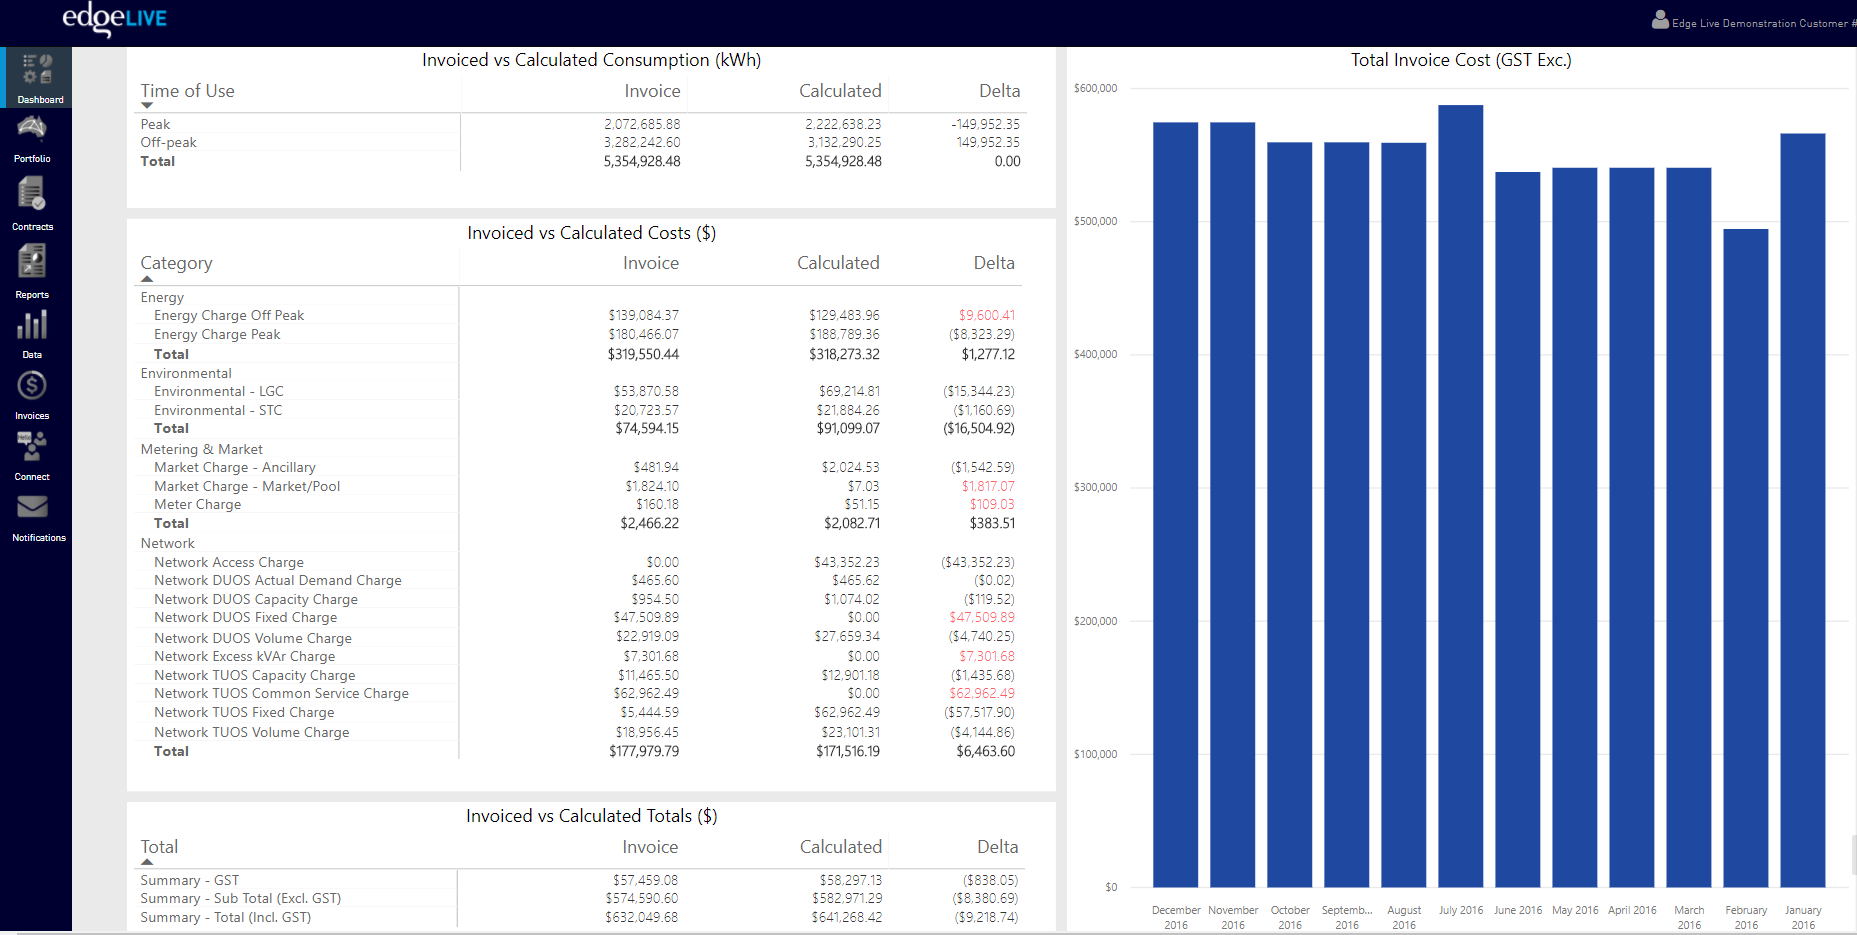
Your Edge Portfolio Manager undertakes your Invoice Reconciliation services the same business day that your final invoice is issued by your Retailer.  From here, the payment advice and outcomes are published instantly on Edge Live. You will receive an email notification that the reconciliation outcome is available, with links through to the Invoice Reconciliation Report.  Providing you with details of the invoice outcome, broken down to the detailed levels of energy, network, markets and other costs.

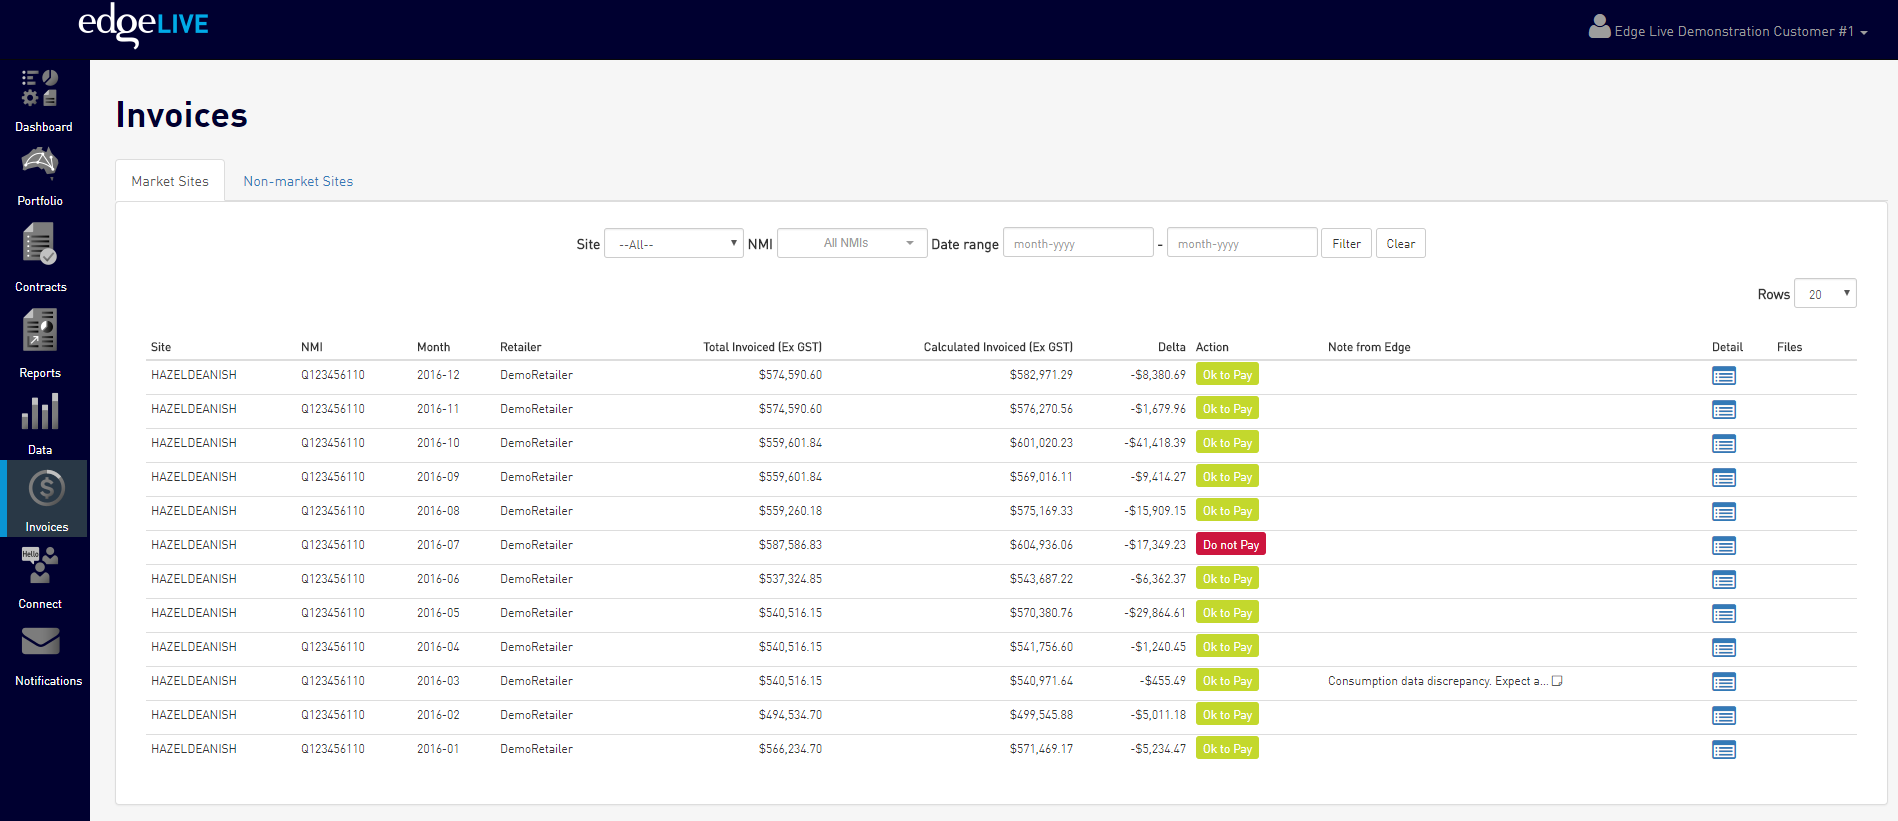
Figure 1 Invoice reconciliation outcome in detail.

Viewing the results is easier and more efficient than ever before.  View them in Edge Live directly from your web browser rather than having to open excel and find the information relevant to you.  Though if you need to, the data can be exported to excel easily with the click of a button within Edge Live.

You will be provided with the invoice reconciliation outcomes, advice on whether to pay or not to pay and any additional personalised comments from your Portfolio Manager relating to your portfolio and individual sites.

Figure 2 Invoice reconciliation notification at an invoice level.

Your monthly Accruals reporting is also available via the online portal. Again, providing an easy and efficient way to advise your finance teams what the expected electricity spend of your portfolio will be as you near the end of each month.

And don’t forget about the existing Dashboard module.  Filter by site and drill-down on specific time-frames of your electricity portfolio so that you can get a clearer view of consumption and costs.

Your Portfolio Manager will be in touch soon to discuss these new features with you, and ensure you have access to Edge Live as well as answer any questions you may have.

We have some exciting features planned for the remainder of 2018. If you have any feedback or suggestions on how Edge Live can be of more value to your business please do not hesitate to let us know, and we will do our best to incorporate this into our Edge Live development roadmap.

To learn more about Edge Live functionality click here, or speak with your Edge Portfolio Manager.

Help Sick Kids Today!

The Children’s Hospital Foundation helps sick kids today and tomorrow by funding life-saving medical research, investing in vital new equipment, and providing comfort, entertainment, support and care for children and their families.

To support this great charity, Edge will be attending The Coffee Club Telethon Ball for the 2nd year running on the 18th of this month.

Unfortunately this event sold out quickly, however there’s a lot you can do to support a child with an injury, serious illness or life threatening disease. You can donate money to help save precious young lives. Donate your time to make a difference at our children’s hospital. Or raise funds for vital research and equipment, spread smiles and support families through difficult times.

You can make a difference to sick kids and their families today and tomorrow. To find out more visit the Children’s Hospital Foundation site at www.childrens.org.au and be sure to tune into Channel 9, Saturday 19 November for the annual Telethon.

EDGE LIVE – Introducing interactive ‘Dashboards’

We’re all about providing a tailored and specialised service to our clients. But we also know you often need quick access to information regarding your energy consumption and spend. This is why we’ve developed Edge Live.

Edge Live is a secure, online information portal that gives you instant access to contracts, portfolio information, reports, data and so much more. The portal provides you with instant access to the information you need to make informed choices for your business.

Our latest enhancements to the Edge Live software is our interactive Dashboard module.

Interactive Dashboards

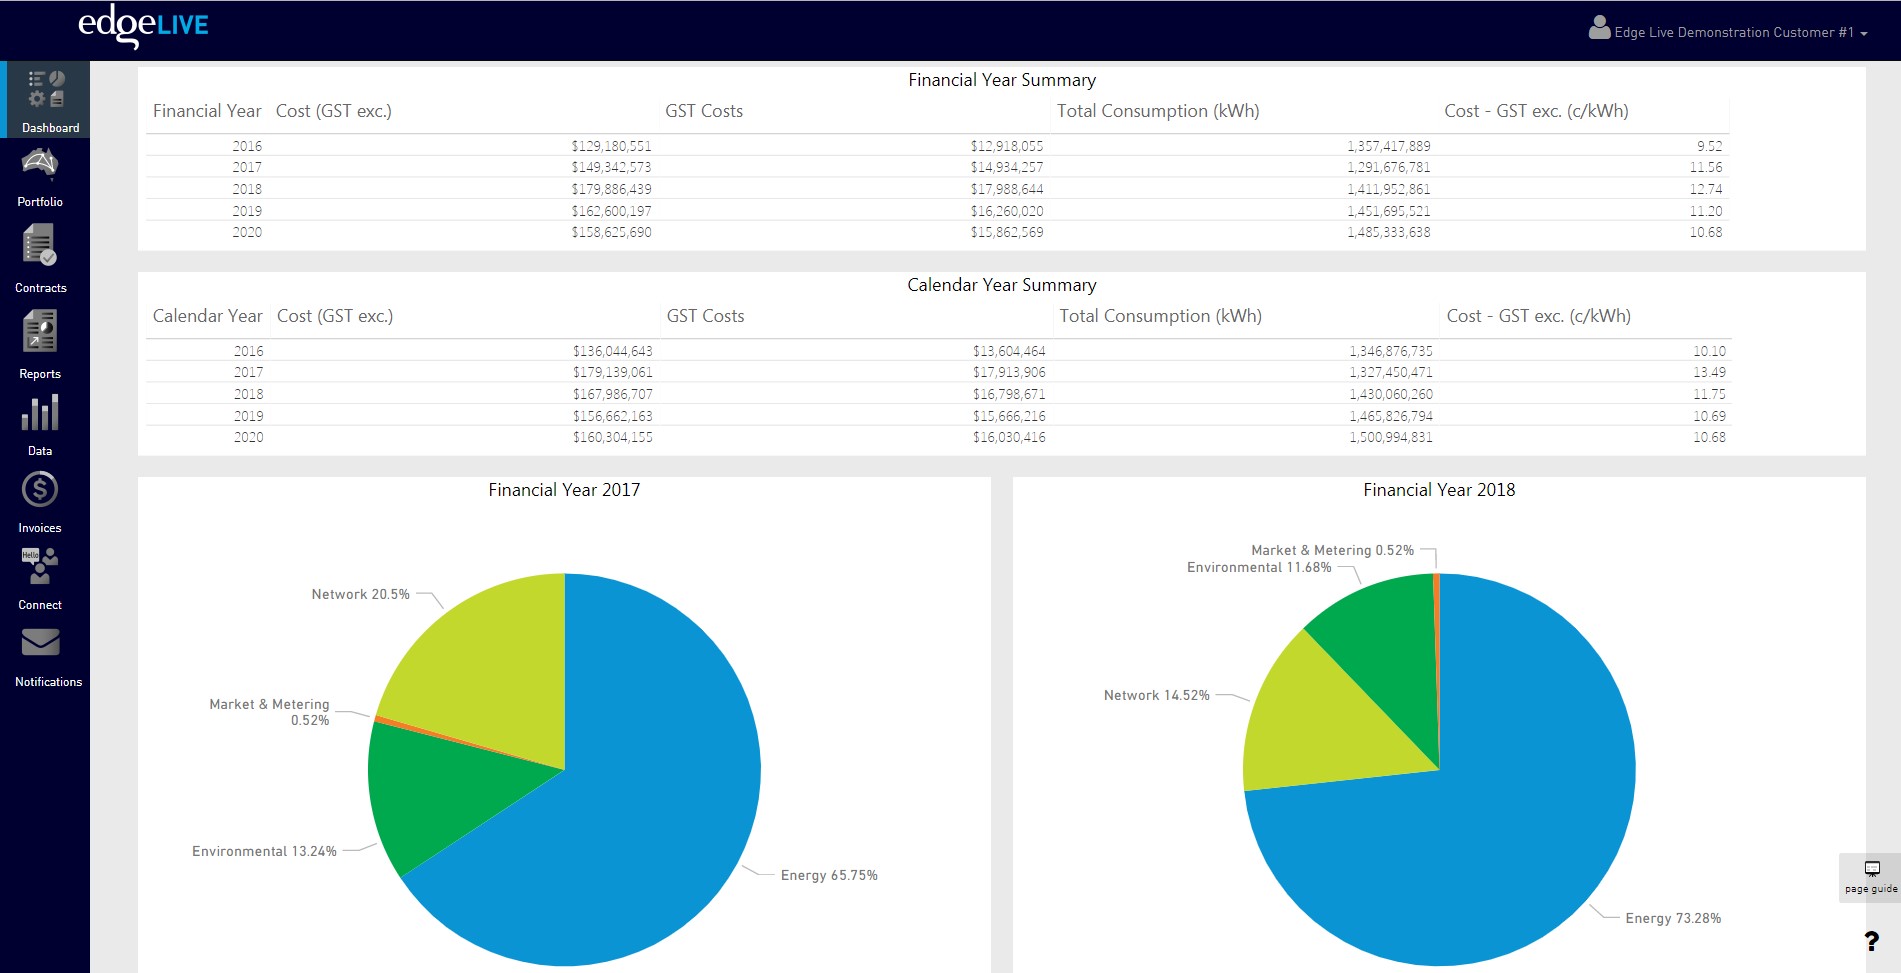
Edge Dashboard provides you with an interactive graphical portal that allows you to view your consumption and energy costs across a chosen period.  The functionality of the dashboard allows you to filter data to a specific financial or calendar year, whilst also providing you with the ability to set your own date range.

Figure 1 Cost data being displayed by financial and calendar year both in table and graphical format.


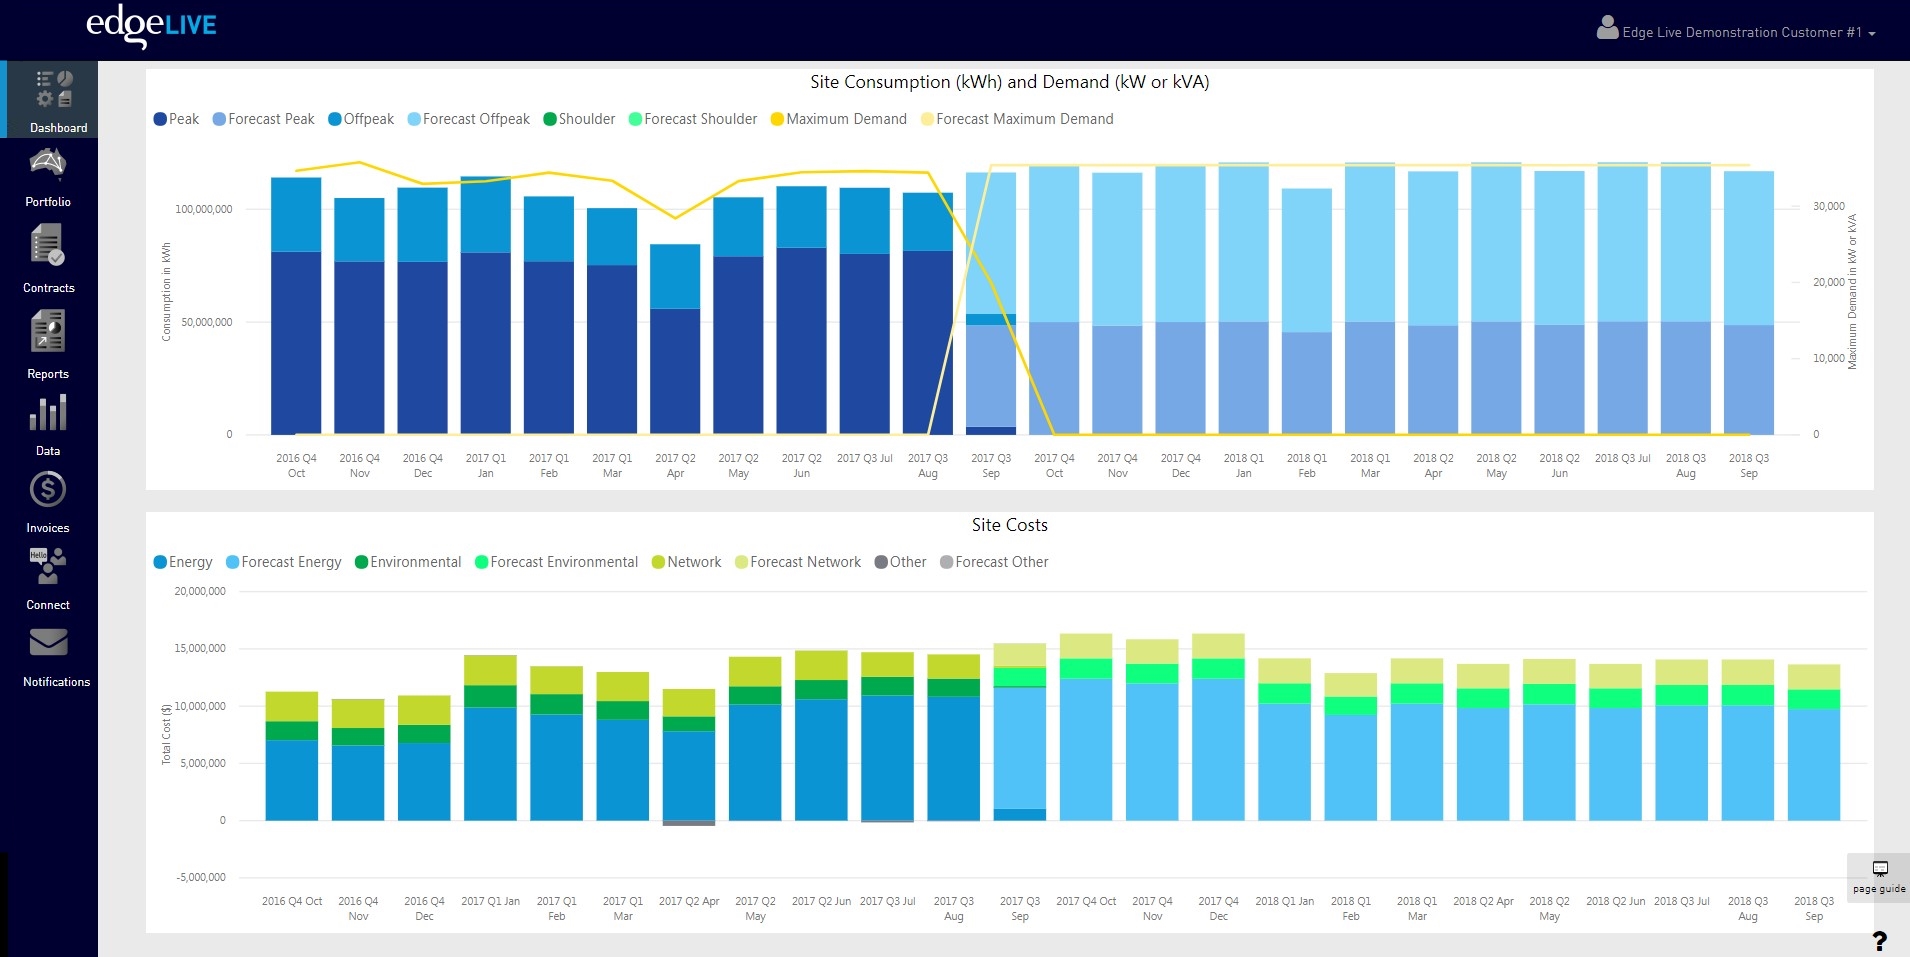
It also provides you with the ability to drill down to specific sites and/or regions, depending on the portfolio or type of reporting that you wish to obtain information for.

Figure 2 Graph illustrating site consumption and demand across a period of months and a graph illustrating site costs across a period of months.


If you require more information than the standard dashboard provides, bespoke dashboards can be prepared for you in conjunction with our in-house IT Team and your dedicated Portfolio Manager.

Other Interactive Modules

Edge live has many modules that will provide you with valuable data and information that is critical to managing your energy portfolio. These modules include:

  • Counterparty contracts;
  • Portfolio information;
  • Reports, and
  • Data.

To read more about Edge Live functionality click here, and call your Portfolio Manager on 07 3905 9220 to book in a demonstration.

STATE OF THE MARKET – Q417 MARKET OVERVIEW

The electricity market is in a state of confusion as a result of poor Federal and State Government policy. The Market Operator, AEMO, released the Electricity Statement of Opportunities during September. The Statement warned of supply shortfalls during the first three months of 2018 and a heightened risk of unserved energy over the next 10 years.

On 17 October the Federal Government announced the National Energy Guarantee (NEG). The Guarantee is the model that will see energy being delivered to consumers reliably and affordably whilst also meeting our international emission commitments. The NEG is an alternative to the Clean Energy Target introduced by Dr Alan Finkel in his Finkel Review. Since the announcement of the NEG, there has been minimal feedback by the Federal Opposition and some of the State Governments. These governments have made it clear they are waiting on further detail before giving their support. Without support from these governments it will be difficult for the NEG to get off the ground. Edge are awaiting further announcements and modelling from the Federal Government as there is insufficient detail to form a view on the impacts or functionality of the Guarantee for producers and consumers of energy.

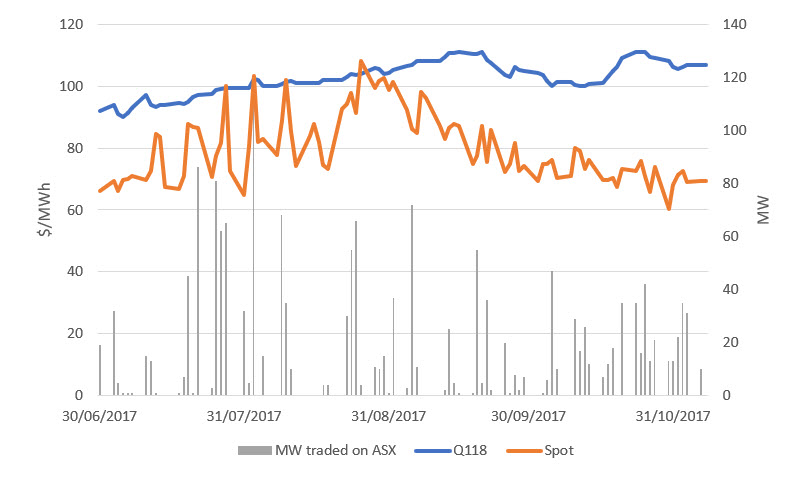
The combination of forecast shortfalls in energy supply, and a national energy policy that lacks detail, has resulted in the price of forward contracts creeping up despite softening spot prices. This has been particularly evident in NSW.

Figure 1 NSW daily average spot price verse CAL18 price and volume traded on the ASX.


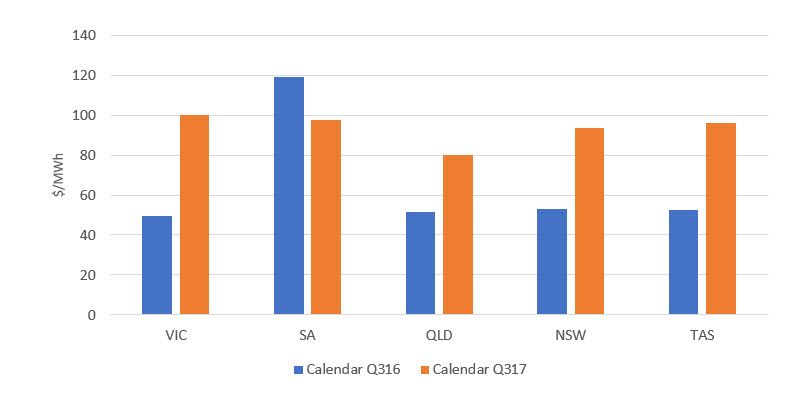
With the exception of SA, average spot prices for Q317 are significantly higher than Q316 prices.  This represents a fundamental shift in the market.

VIC

SA QLD NSW TAS
Calendar Q317 100.01 97.74 79.93 93.57

95.84


Table 1 Q317 average spot prices as at 7 November 2017.


Figure 2 Q316 verse Q317 average spot prices.


With valid concern around shortages in supply, medium to large energy consumers are looking for alternatives to reduce costs and/or hedge price risks. A credible alternative is a Power Purchase Agreement (PPA); entered into directly with a generator. PPAs can be facilitated with any kind of generator that is willing to offer one. Typically, these are renewable energy projects offering 10 – 20 year agreements at defined prices. This type of offtake agreement is generally required prior to a new renewable project receiving financing. Offtake agreements from renewable projects do not suit all customers and the following points are some key considerations that should be taken into account before entering a PPA with a renewable generator:

  • Ability to commit to a volume and price for 10 or more years
  • Correlation of your demand and the output profile of the renewable generator
  • Business view on hedging commodities

Click here if you would like to read more about how Edge is assisting customers to reduce costs through the implementation of PPA’s.

Supply Near Term outlook

Spot prices are expected to be volatile and high due to a shortage in supply. Particularly in the first three calendar months of 2018 in SA and VIC. This expectation is a driver behind the Reliability and Emergency Reserve Trader (RERT) and a reason for forward contracts being traded at high prices.

VIC SA QLD NSW
Q118 146.00 159.00 105.35

106.76


Table 2 Q118 Forward Contract Prices as at 7 November 2017.


The second round of the Long Notice RERT was released on 6 September 2017. The purpose of the RERT is to provide AEMO with the capability to maintain power system reliability and system security by utilising reserve contracts. In order to become a member of the RERT Panel, panellists need to either provide generation or load reduction.

Submissions were due on 20 September and contracts are required to be executed by the 31 October 2017. Currently, there is a Medium to Short Term RERT open to tender which is scheduled to close on 17 November. Participants are asked in this tender what their reserve availability will be in the period 1 November 2017 to 31 March 2018.

The recent commitment from LNG producers to make more gas available to the domestic market should alleviate some of the predicted high electricity prices.  It has to be noted however, that this additional gas is in QLD which is a long way from SA and VIC where the main concerns sit. This gas is more likely to relieve prices in QLD which in turn should help to mitigate high spot prices in NSW, though impacts will be marginal further south.